

Packaged foods company General Mills (NYSE:GIS) reported Q3 CY2026 results beating Wall Street’s revenue expectations, but sales fell by 2.8% year on year to $4.39 billion. Its non-GAAP profit of $0.75 per share was 4.5% above analysts’ consensus estimates.
Is now the time to buy General Mills? Find out by accessing our full research report, it’s free.
General Mills (GIS) Q3 CY2026 Highlights:
- Revenue: $4.39 billion vs analyst estimates of $4.35 billion (2.8% year-on-year decline, 0.9% beat)
- Adjusted EPS: $0.75 vs analyst estimates of $0.72 (4.5% beat)
- Operating Margin: 14.4%, down from 38.2% in the same quarter last year
- Free Cash Flow Margin: 4.7%, down from 6.4% in the same quarter last year
- Organic Revenue was flat year on year (beat)
- Sales Volumes fell 4% year on year (-8% in the same quarter last year)
- Market Capitalization: $18.95 billion
Company Overview
Best known for its portfolio of powerhouse breakfast cereal brands, General Mills (NYSE:GIS) is a packaged foods company that has also made a mark in cereals, baking products, and snacks.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but many enduring ones grow for years.
With $18.3 billion in revenue over the past 12 months, General Mills is larger than most consumer staples companies and benefits from economies of scale, enabling it to gain more leverage on its fixed costs than smaller competitors. Its size also gives it negotiating leverage with distributors, allowing its products to reach more shelves. However, its scale is a double-edged sword because there are only a finite number of major retail partners, placing a ceiling on its growth. For General Mills to boost its sales, it likely needs to adjust its prices, launch new offerings, or lean into foreign markets.
As you can see below, General Mills struggled to generate demand over the last three years. Its sales dropped by 3.4% annually as consumers bought less of its products.
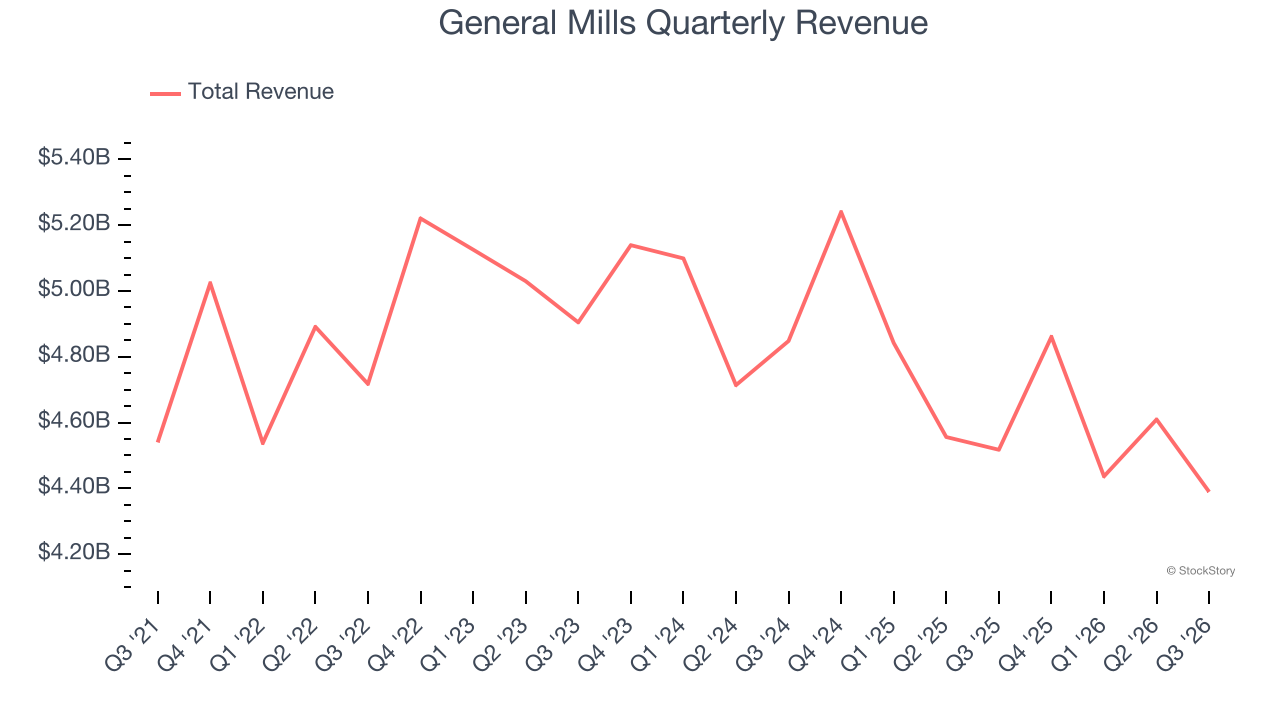
This quarter, General Mills’s revenue fell by 2.8% year on year to $4.39 billion but beat Wall Street’s estimates by 0.9%.
Looking ahead, sell-side analysts expect revenue to decline by 3% over the next 12 months, similar to its three-year rate. This projection is underwhelming and suggests its newer products will not catalyze better top-line performance yet.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Volume Growth
Revenue growth can be broken down into changes in price and volume (the number of units sold). While both are important, volume is the lifeblood of a successful staples business as there’s a ceiling to what consumers will pay for everyday goods; they can always trade down to non-branded products if the branded versions are too expensive.
To analyze whether General Mills generated its growth (or lack thereof) from changes in price or volume, we can compare its volume growth to its organic revenue growth, which excludes non-fundamental impacts on company financials like mergers and currency fluctuations.
Over the last two years, General Mills’s average quarterly volumes have shrunk by 4.9%. This isn’t ideal for a consumer staples company, where demand is typically stable. In the context of its 1.8% average organic sales declines, we can see that most of the company’s losses have come from fewer customers purchasing its products.
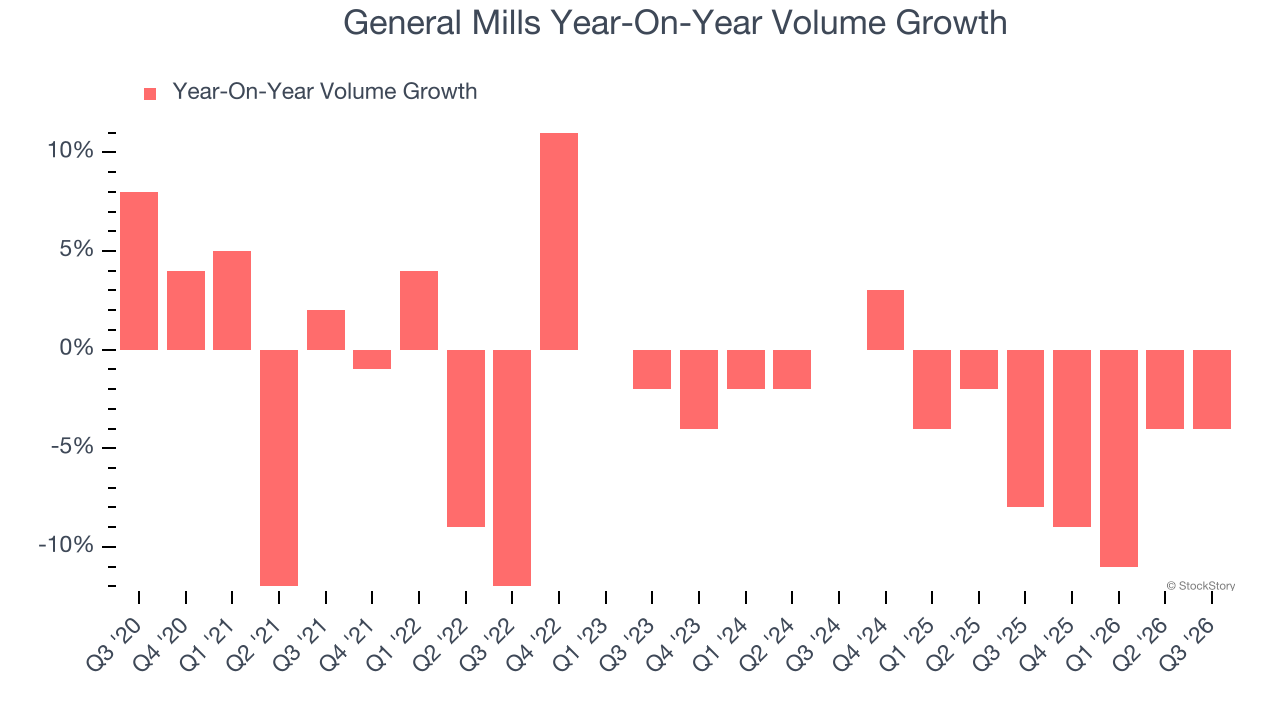
In General Mills’s Q3 2026, sales volumes dropped 4% year on year. This result represents a further improvement from its historical levels.
Key Takeaways from General Mills’s Q3 Results
It was encouraging to see General Mills beat analysts’ organic revenue expectations this quarter. We were also happy its gross margin outperformed Wall Street’s estimates. Overall, this print had some key positives. The stock remained flat at $35.46 immediately after reporting.
General Mills had an encouraging quarter, but one earnings result doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).