
What a fantastic six months it’s been for Arrow Electronics. Shares of the company have skyrocketed 68.9%, hitting $230.24. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is now the time to buy Arrow Electronics, or should you be careful about including it in your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Is Arrow Electronics Not Exciting?
We’re happy investors have made money, but we don’t have much confidence in Arrow Electronics. Here are three reasons why there are better opportunities than ARW, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
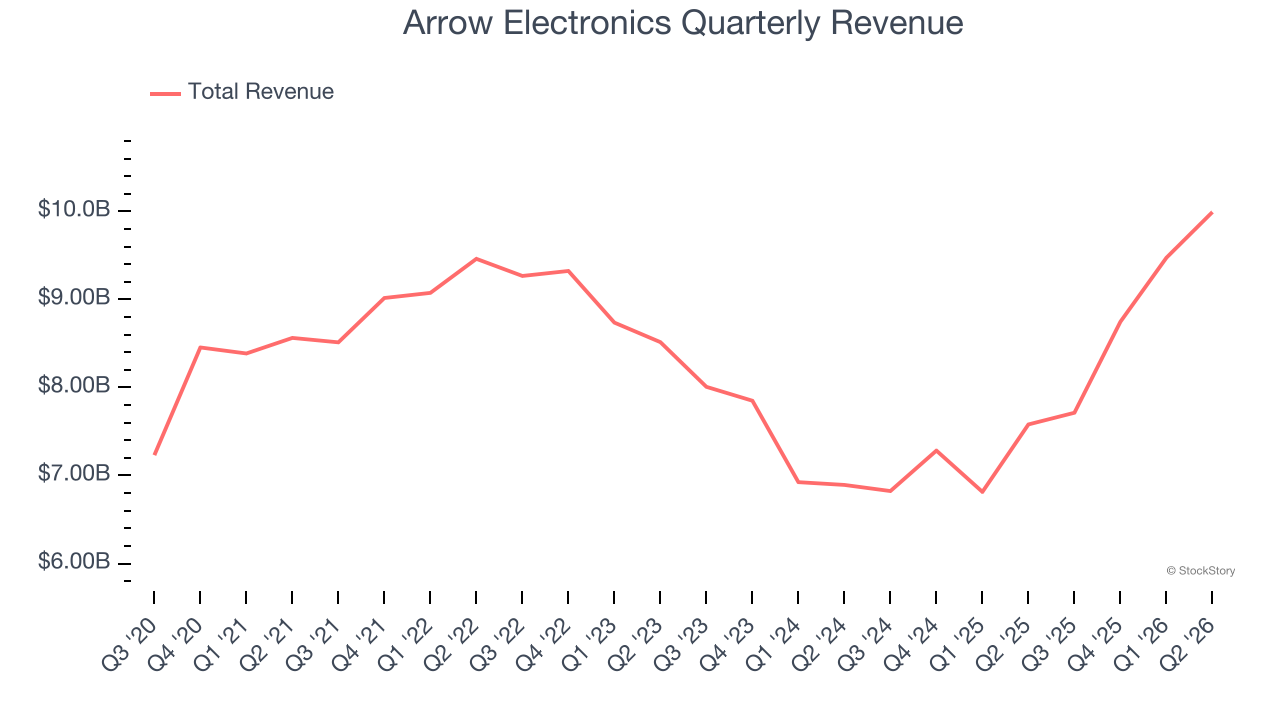
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Arrow Electronics grew its sales at a sluggish 1.9% compounded annual growth rate. This fell short of our benchmarks.
2. Low Gross Margin Reveals Weak Structural Profitability
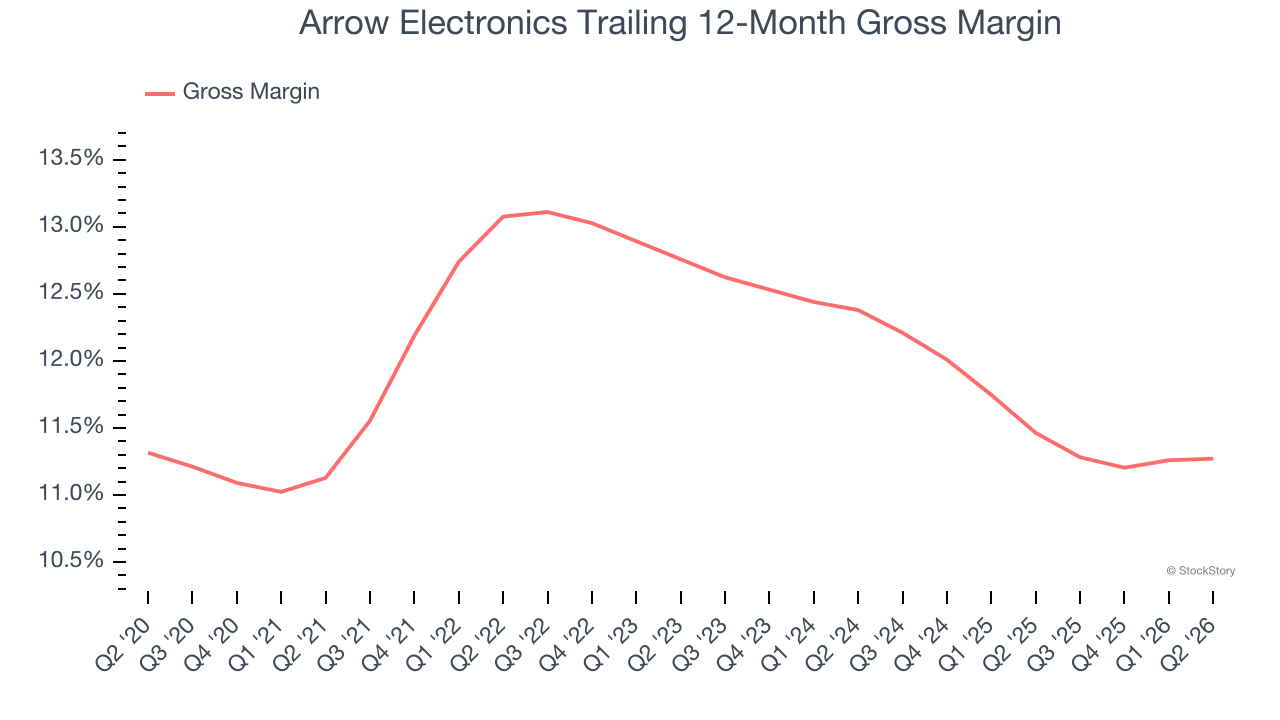
All else equal, we prefer higher gross margins because they make it easier to generate more operating profits and indicate that a company commands pricing power by offering more differentiated products.
Arrow Electronics has bad unit economics for an industrials business, signaling it operates in a competitive market. As you can see below, it averaged a 12.2% gross margin over the last five years. Said differently, Arrow Electronics had to pay a chunky $87.78 to its suppliers for every $100 in revenue.
3. New Investments Fail to Bear Fruit as ROIC Declines
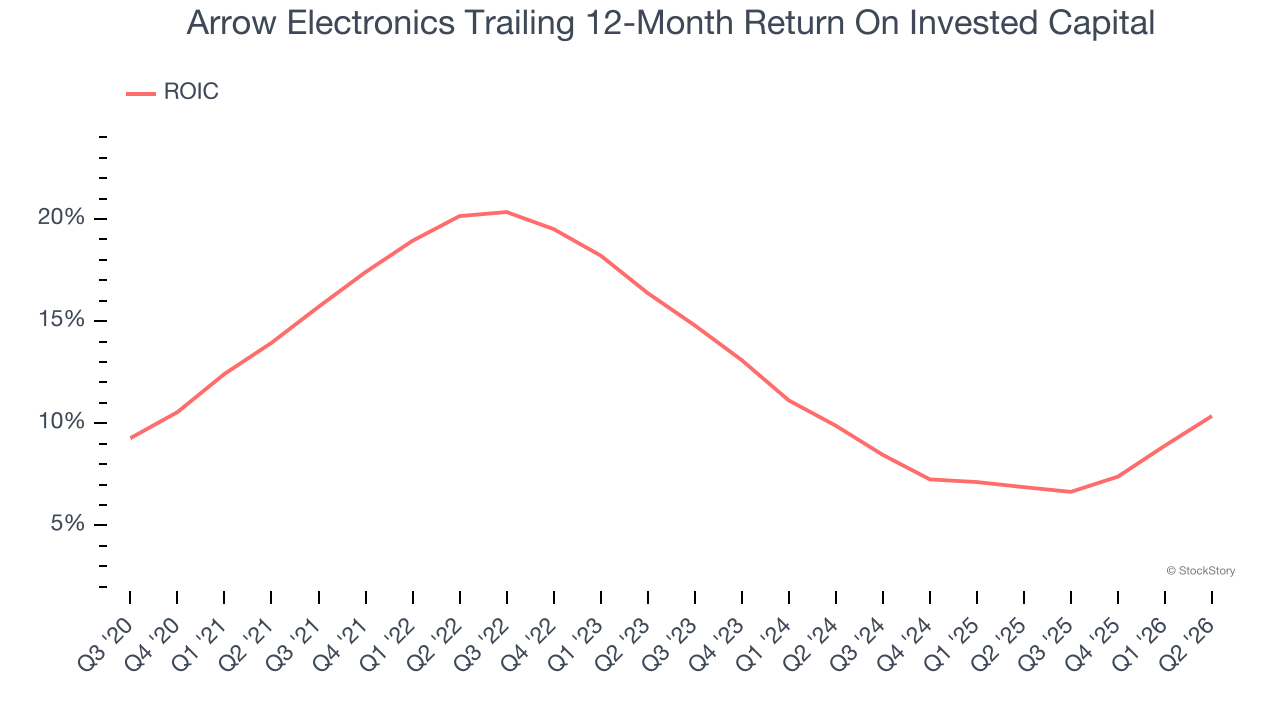
We like to invest in businesses with high returns, but the trend in a company’s ROIC can also be an early indicator of future business quality.
Over the last few years, Arrow Electronics’s ROIC has unfortunately decreased. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Arrow Electronics isn’t a terrible business, but it doesn’t pass our quality test. Following the recent surge, the stock trades at 10.4× forward P/E (or $230.24 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d recommend looking at the most entrenched endpoint security platform on the market.
Stocks We Like More Than Arrow Electronics
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.